

The New Defense Economy Demands Speed, Scale and Staying Power

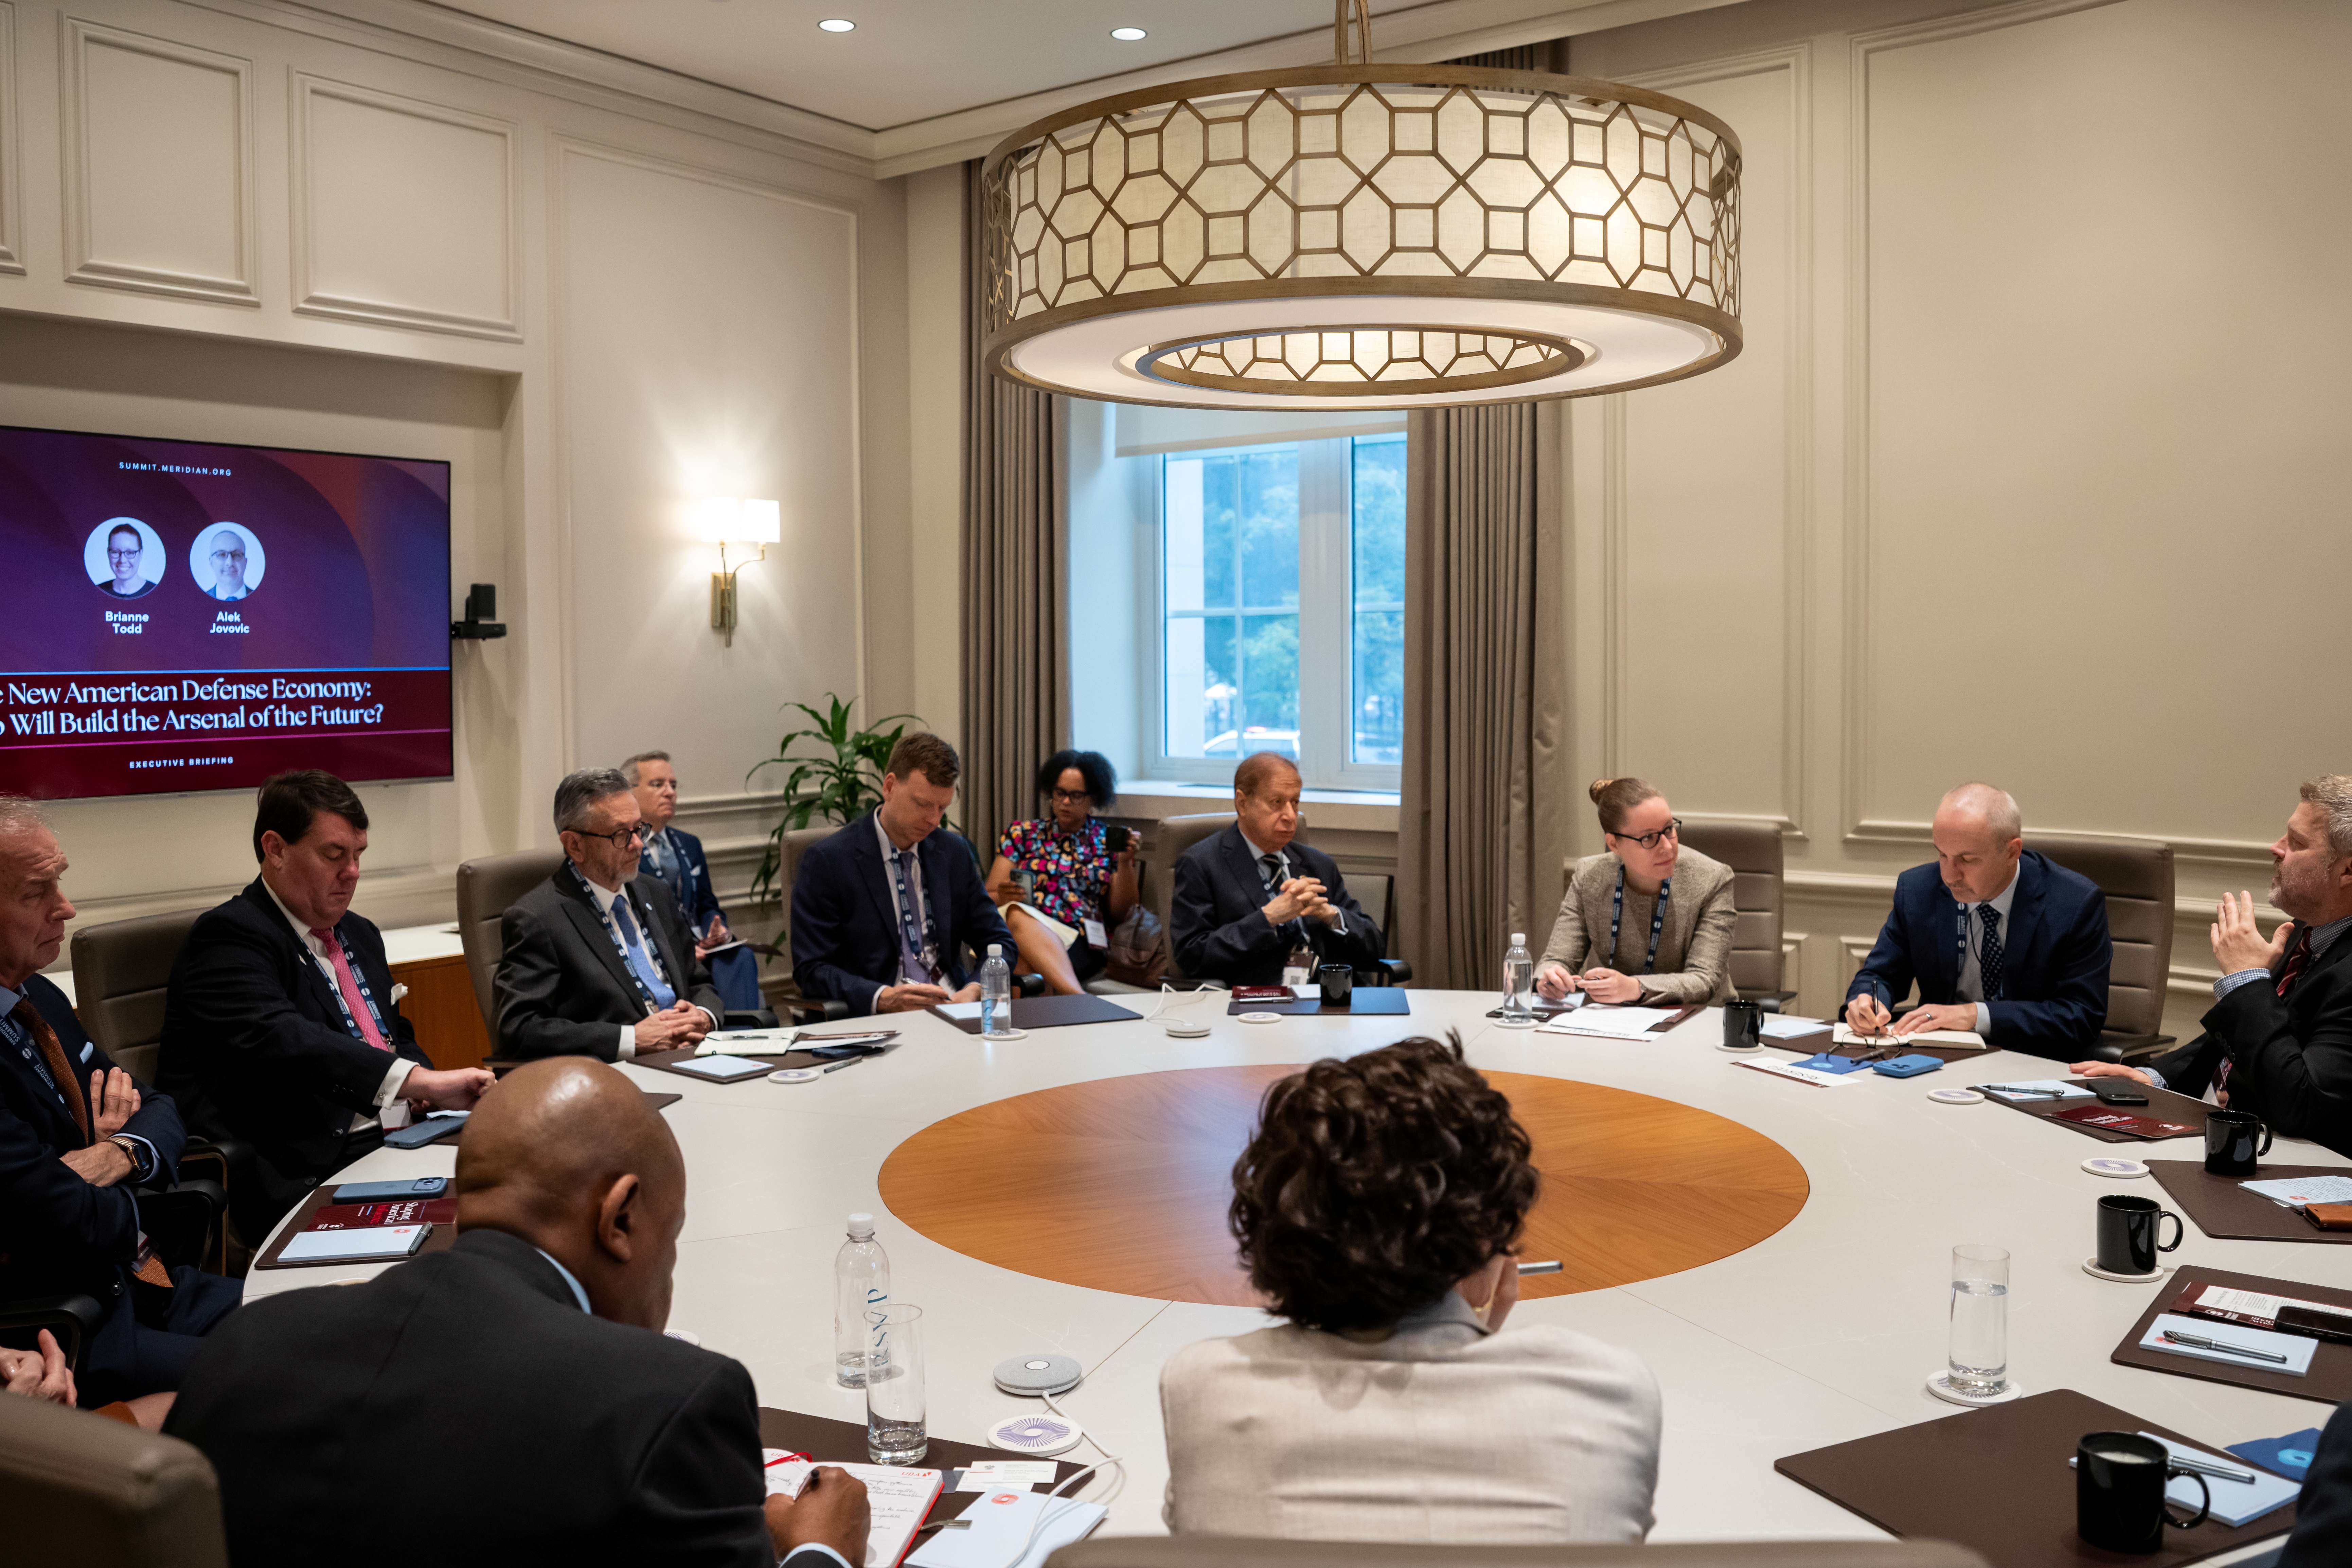
On the sidelines of the 15th annual Meridian Summit held on October 16, 2026, Meridian convened an Executive Briefing “The New American Defense Economy: Who Will Build the Arsenal of the Future?” examining how recent conflicts are reshaping military power and the defense economy. The discussion featured Alek Jovovic, Deputy Director, Center for the Industrial Base and Senior Fellow for the Defense and Security Department at the Center for Strategic and International Studies, alongside Brianne Todd, Professor of the Practice, Near East South Asia Center for Strategic Studies and the National Defense University. The conversation explored how the United States can strengthen its industrial base, accelerate innovation and sustain military readiness amid increasingly complex global threats.
Discussion participants emphasized that future military advantages will depend on more than developing cutting-edge weapons. It will also require the capacity to produce equipment at scale, repair and replenish existing systems, secure vulnerable supply chains, and work more effectively with allies and emerging defense companies.
Here are the top takeaways:
1. Mass Is Back, but More Drones Alone Will Not Secure the Future
Recent conflicts have demonstrated the disruptive power of inexpensive drones, missiles and other uncrewed systems, but replicating another country’s battlefield model is not a strong enough strategy. Ukraine’s rapid adoption of commercially developed systems offers important lessons in speed and decentralized innovation, yet the United States must prepare to project power across long distances and contested logistics networks rather than assume future wars will resemble today’s front lines. Research on Ukraine’s defense transformation underscores the value of commercial technology and bottom-up innovation, while the discussion cautioned against investing heavily in systems that could become obsolete before they are needed.
2. The Defense Industrial Base Must Be Designed to Adapt
The United States cannot predict every capability a future conflict will require, making flexible production capacity as important as today’s inventory. Instead of stockpiling millions of identical systems, the defense sector should expand transportable manufacturing, build reserves of long-lead components, and design equipment that can be updated as technology and battlefield conditions change. Current acquisition reform efforts similarly emphasize open-system architecture, earlier testing and the ability to integrate components from multiple suppliers, all of which could help the military field new capabilities faster without locking itself into a single design or company.
3. Readiness Begins With Maintaining What the Military Already Owns
New platforms offer little strategic value if existing aircraft, ships and ground vehicles are unavailable because of maintenance backlogs, missing parts, or insufficient technical data. The Government Accountability Office found that none of the Army vehicles it reviewed met the service’s 90% availability goal in fiscal 2024, while mission-capable rates declined for 16 of the 18 Army and Marine Corps vehicle types examined between fiscal years 2015 and 2024. GAO also found that shortages of parts, skilled maintainers and current technical information were persistent barriers to readiness, reinforcing the discussion’s central point: sustainment must be treated as a war-fighting capability, not a secondary budget consideration.
4. The Weakest Suppliers May Be the Defense Sector’s Biggest Vulnerability
Defense resilience depends not only on major contractors but also on smaller manufacturers that produce specialized batteries, actuators, machine parts, and other components buried deep in the supply chain. Many of these businesses are single-source suppliers, creating potential bottlenecks that can delay production across multiple weapons programs. Drone manufacturing illustrates the broader challenge: specialized composites, batteries, semiconductors, and rare-earth materials can become strategic chokepoints when they are sourced from, or processed by, a potential adversary. Strengthening the industrial base will therefore require greater visibility into lower-tier suppliers, faster qualification of alternatives and sustained investment in small and midsize manufacturers.
5. Allied Production Must Move from Interoperability to Interchangeability
Allies have long focused on ensuring that their forces can operate together, but future readiness will increasingly depend on whether they can also build, repair, and replace one another’s equipment. Expanded co-production, licensing and mutual qualification of suppliers could give the United States and its partners access to more manufacturing capacity while reducing dependence on fragile national supply chains. Common components and technical standards would make it easier to source a part in one allied country and use it in another’s system, but intellectual property and data-rights restrictions remain significant barriers. GAO has warned that data-rights shortfalls can leave the Defense Department dependent on a single supplier, increasing costs and extending repair timelines.
Project summary
| The New Defense Economy Demands Speed, Scale and Staying Power | October 2026 | |
|---|---|
| Program Areas: | Diplomatic Engagement |
